
The Supreme Court on October 29 said banks and financial institutions must compensate victims of cyber fraud digital arrest where investigation shows the loss followed a failure to exercise due diligence and stop suspicious transactions. A Bench led by Chief Justice Surya Kant with Justices Joymalya Bagchi and V. Mohana laid down the compensation principle while hearing matters concerning digital-arrest frauds, and called for tighter transaction-monitoring safeguards across the banking system.
Banks will not turn into automatic insurers for every online fraud under the direction. Payment depends on a finding in the probe that the institution failed to act as a careful financial intermediary should have acted. Where money moved through accounts despite red flags that existing systems should have caught, the bank concerned will have to make good the loss to the extent assessed. Fault, established during investigation, will decide relief, instead of pushing victims to file separate civil suits after the criminal case ends.
Account holders who lost savings in recent months will feel that shift first. Police complaints in such cases often end with a few accounts frozen long after funds have travelled through multiple layers. Recovery then becomes difficult. By fixing responsibility on the institution that handled the transaction and failed to raise an alert, the Court has given victims a clearer route to restitution that runs alongside the criminal investigation, not after it.
Compensation tied to failed checks
Prevention was the Bench's second concern. It said banks must strengthen systems to detect and hold suspicious transactions before the money leaves the system. The emphasis in court was on real-time monitoring, quick flagging of unusual credits and debits, and prompt action once an account is seen to be used as a conduit for fraud proceeds. The Court did not prescribe the technology or thresholds, but it made clear that the absence of effective checks will weigh against the institution when compensation is considered.
In practice, the test will turn on records. Whether the bank had rules for high-risk transfers, whether its software generated alerts, whether staff acted on them and whether authorities were informed in time will be answered from transaction logs, internal alerts and correspondence with law enforcement. A victim will still need to show the trail of the fraud, while the bank will need to show what its system did when the trail passed through it.
Why cyber fraud digital arrest spreads
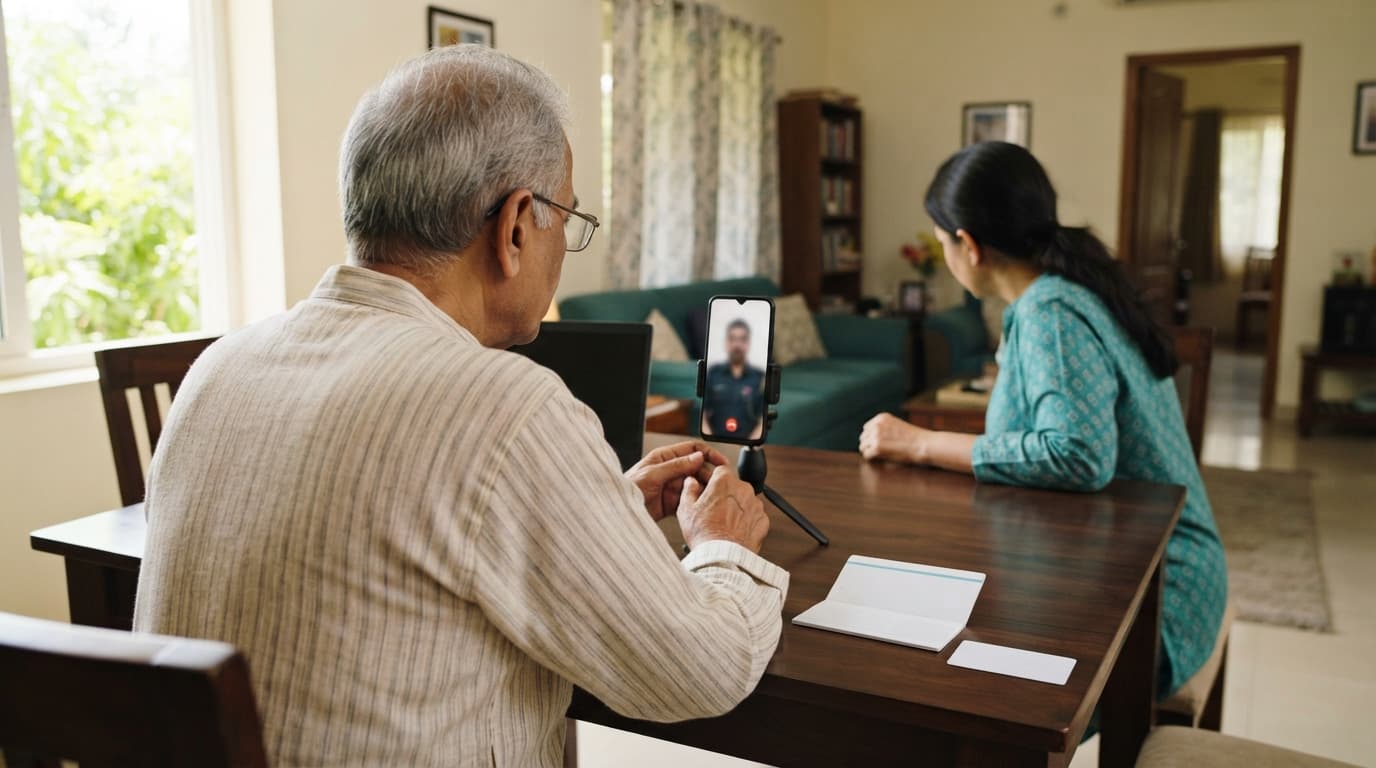
To understand the direction, it helps to ask what is digital arrest fraud in the form now reaching courts and police stations. Callers posing as police, customs, narcotics or investigation officers contact the victim over phone or video call and claim the victim is linked to a crime, money laundering or a parcel containing drugs. They then order the person to stay online, forbid contact with family, stage a fake hearing or verification, and demand transfer of money to so-called safe or verification accounts. Fear and isolation do the rest.
Many readers searching in Hindi for digital arrest fraud kya hai are looking for the same answer in simpler terms. It is not a real arrest. No law permits arrest over a video call or payment for release through fund transfer. The fraud uses fake uniforms, logos, documents and threats of immediate arrest to force quick payment before the victim can check. Genuine officers do not ask for money to keep a person out of custody, courts have said.
Cases before the Supreme Court sit against a steady rise in such complaints, where the first transfer is followed within minutes by onward transfers through mule accounts. Once the chain lengthens, recovery depends on how fast the originating and receiving banks act. That link explains why the Court connected compensation to diligence. A bank that spots an abnormal pattern and pauses the transaction can break the chain. A bank that lets it pass without inquiry allows the loss to become final.
RBI list and police reports
The Court directed the Reserve Bank of India to furnish a list of authorised institutions to be covered by its proposed regulatory framework. The list will define the perimeter of the new safeguards, so obligations on monitoring, reporting and customer protection apply evenly and no entity handling public funds slips through gaps. The Bench did not set out the contents of the framework, but sought the list as a first step toward putting it in place.
Police chiefs of states and Union Territories must report digital-arrest cases, investigations and preventive steps to the inter-departmental committee examining the issue. Those reports will give the committee a national picture: how many cases have been registered, what stage investigation has reached, what amounts have been frozen or recovered, and what advisories, helplines and coordination with banks are in use. The collation is meant to move the response from isolated first information reports to a shared record that can guide policy.
The order brings the liability of bank institutions into sharper focus than earlier circulars and consumer forum decisions. Until now, many victims were told to wait for the criminal process or to prove negligence in separate proceedings. The present direction keeps the criminal track alive but adds a compensation track linked to the findings of investigation. If the probe finds the bank failed to check a suspicious transaction, relief need not wait for conviction of the fraudster, who often remains untraced.
Legal responsibility is what the Court spoke of, not book-keeping. The direction does not turn on questions such as is bank overdraft a current liability in a company's accounts, or whether bank is asset or liability on a depositor's balance sheet, or whether is bank loan a current liability for accounting purposes. It also does not deal with liability products of bank marketing, such as savings accounts and deposits. Those classroom and compliance terms describe how money is recorded. The issue here is different: whether the institution that moved the money exercised care before moving it.
Listed again before November 30, the matter will return with the Reserve Bank's list, the collated reports from police chiefs, and an update from the inter-departmental committee on the proposed framework. For now, the immediate task for both sides is documentation. Complainants will need to preserve call records, transaction messages and complaint numbers, while institutions will need to produce monitoring logs and action-taken reports. Payment, where ordered, will follow the finding of failure, not the fact of fraud alone.
Comments
Sign in to read the discussion and share your thoughts.
Latest from LawWorld
News
View all- Supreme Court Seeks Centre, ECI Reply On Plea Against Immunity For CEC And ECs4 Nov 2026
- Supreme Court Directs MP Speaker To Decide Bina MLA Disqualification Plea In Two Months4 Nov 2026
- Supreme Court Orders Special Cell To Monitor Child Labour Law Enforcement4 Nov 2026
- Bail Cannot Rest On Judge's Personal Notions Of Morality, Rules Supreme Court4 Nov 2026
- Supreme Court Refers Two-Child Norm Penalties To Larger Bench As Outdated4 Nov 2026