What the Court Said on October 29
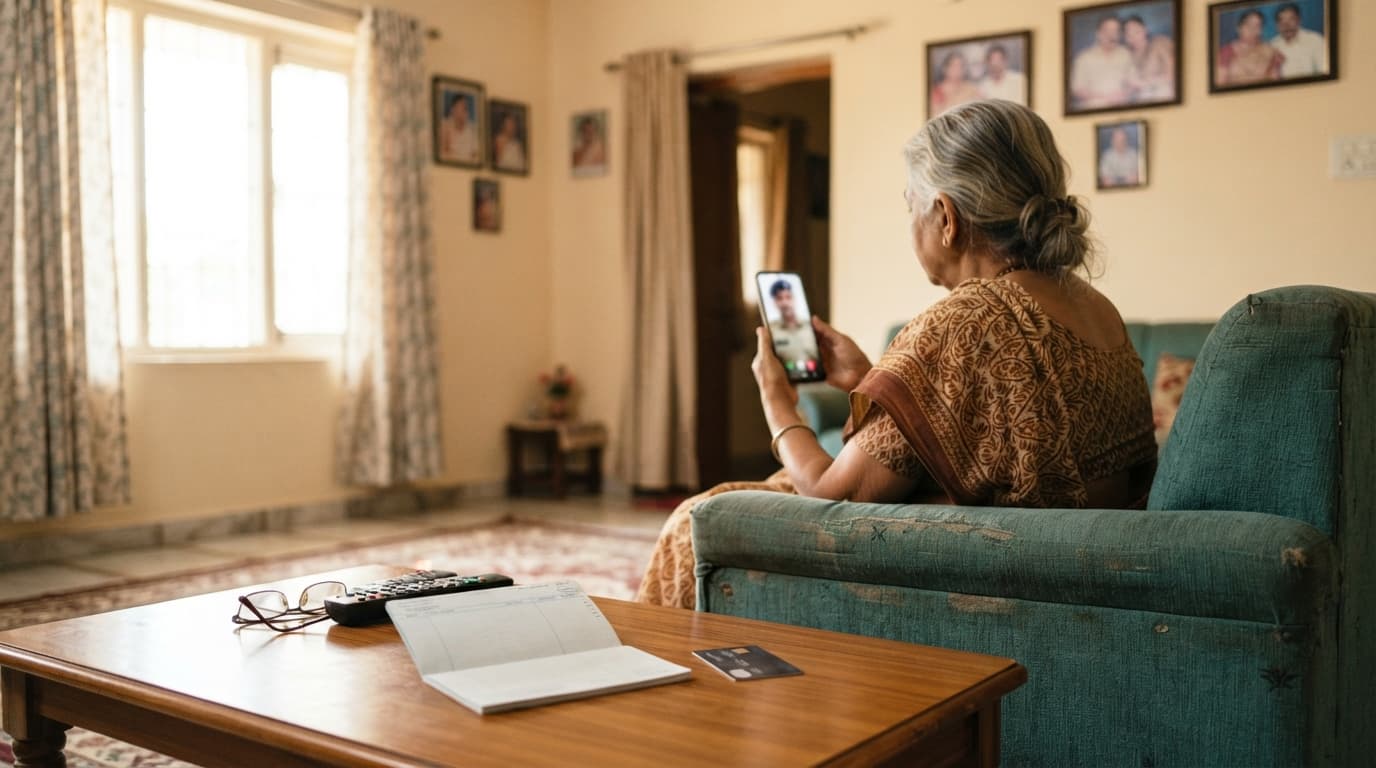
During the hearing, the Bench asked why bank systems let large, unusual transfers pass without a check, a call-back, or a temporary hold. Fraud callers keep victims on continuous video or audio calls for hours. They warn them against contacting family and flash fake arrest warrants or agency logos to create fear. Money then moves fast through mule accounts and is withdrawn or layered before the victim learns there was never any case.
It linked this pattern to a wider drain on household savings and the formal economy. Annual siphoning through such phone-based frauds, the Bench said, is large enough to demand a regulatory response rather than case-by-case sympathy. The answer it suggested was institutional accountability. Where a bank failed to maintain monitoring, velocity checks, mule-account controls, or quick response to suspicious transaction reports, it should make the victim whole.
How Digital Arrest Scams Actually Work
Many readers who type what is digital arrest fraud into a search box get a one-line definition. The lived version is longer and more coercive. A caller claims to be from the police, customs, narcotics control, or a court. The caller says your Aadhaar, parcel, or bank account is linked to money laundering or drugs. Then comes the so-called digital arrest, confinement over a video call pending verification, with threats of instant arrest if you disconnect.
In Hindi the query often reads digital arrest fraud kya hai, and the answer is the same in every language. Indian law has no provision for arrest over a phone call. Police do not hold hearings on Skype or WhatsApp and do not demand money to close a case. This kind of cyber fraud digital arrest works because it borrows the language of procedure, case diary numbers, tribunal orders and money trails, and pairs it with constant watch that leaves little time to think.
The liability of bank for Push Fraud
To see why compensation rules matter, it helps to recall how deposits sit in law. The confusion over cash in bank asset or liability is common, and from the customer's side the answer is plain. The balance is an asset you own. From the bank's side the picture reverses. Deposits are liability products of bank business, money the bank owes you on demand and must repay with interest where promised.
The reverse position explains phrases that puzzle non-accountants. A query like bank overdraft asset or liability comes up because an overdraft looks like cash in hand yet it is money owed to the bank. In company balance sheets the answer to is bank overdraft a current liability is yes, since it is repayable on demand within twelve months. That accounting treatment does not decide fraud liability, but it shows why banks earn from using your funds and must guard them with care.
Authorised push fraud sits awkwardly in present rules. The customer clicks approve, often in fear, while the bank's fraud engine sees an odd payee, a new device, a late-night high-value transfer, or a first-time RTGS to a distant account. Existing grievance channels tend to treat a one-time password or self-approval as proof of customer fault. The Supreme Court's suggestion would change that start. Approval got by deceit during a fake custody call would no longer end the inquiry.
Where Customers Stand on Refunds Today
At present Indian customers rely on a patchwork of remedies. They must report fast on the cyber helpline and portal, inform the branch in writing, file a police complaint, and keep call logs, UPI references, and account statements. Banks examine whether there was a system lapse, whether the complaint was delayed, and whether the customer shared credentials. Outcomes vary widely. Some get interim lien amounts. Many get nothing once funds leave the chain.
Court directions in consumer and writ cases have sometimes ordered relief where banks ignored red flags or delayed freezing mule accounts. Still, there is no uniform rule that says a bank pays in full whenever diligence is missing. That gap is what the October 29 observations address. The Bench wants the Reserve Bank to spell out when indemnity is mandatory, how loss is assessed, and within what time compensation must be credited.
What Banks Will Have to Prove Next
If the regulator acts, banks will need to show concrete diligence in each disputed transaction. That would include real-time risk scoring, limits on first-time payees, cooling periods for high-value additions, vernacular alerts that warn against digital custody threats, and quick action on inward complaints about mule accounts. Records would matter. Logs of SMS and push alerts, device changes, and staff response times would become evidence that safeguards were working or were merely on paper.
For customers the practical lesson stays unchanged while rules are framed. Cut the call, call back the official number of the agency from a fresh line, and speak to family before moving money. Report within minutes, not days, and keep a written trail with transaction IDs. Educated professionals fall for these scripts because fear narrows attention, not because they lack intelligence. A short pause and an independent check break the script.
The next step lies with the Reserve Bank. The Court has asked it to examine a framework for full indemnity where diligence was absent and to return with its position as the matter proceeds. Banks should expect closer scrutiny of anti-fraud controls and grievance timelines. Victims with pending complaints should keep acknowledgements ready, since any new direction on eligibility or timelines will turn on documents that prove when they reported and how the bank responded.