
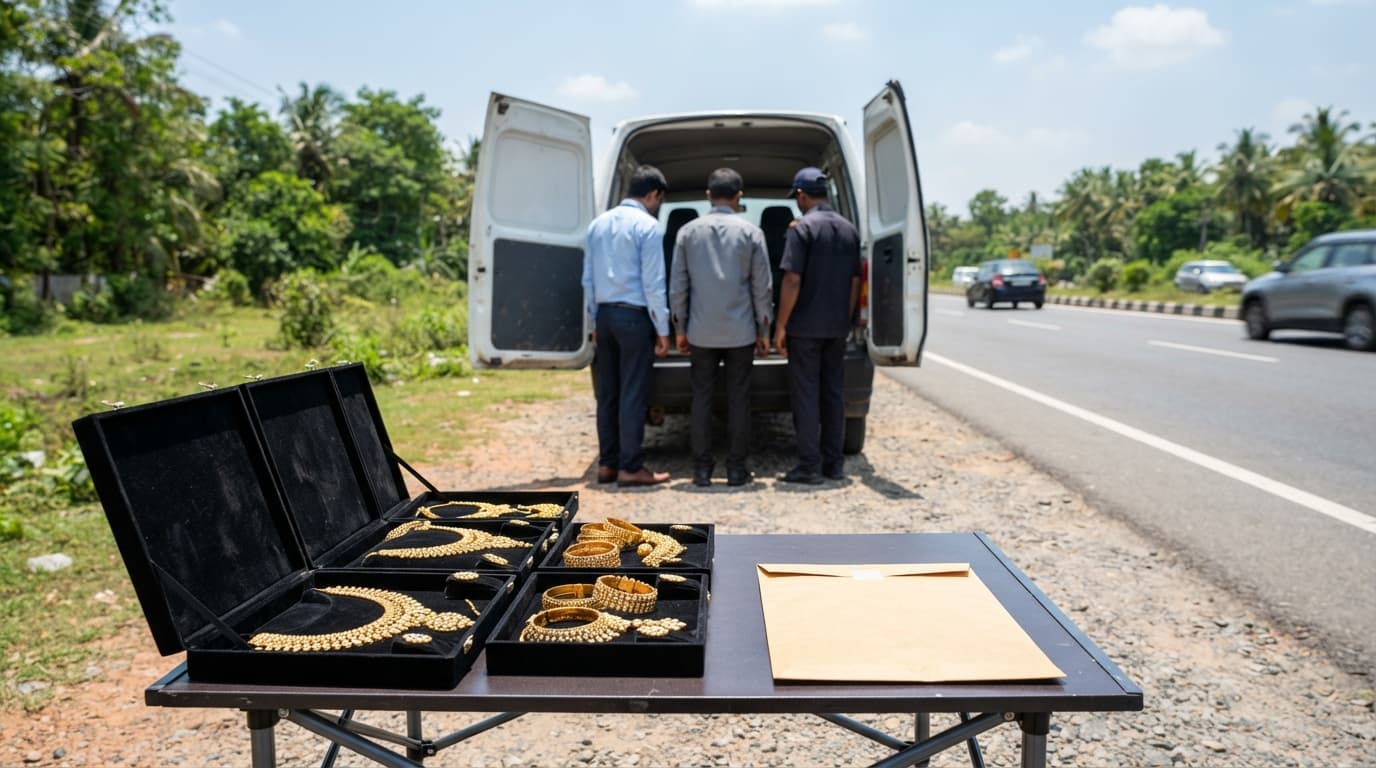
The Karnataka High Court has quashed a GST penalty of Rs 14,50,560 imposed on gold jewellery carried as samples and ordered its refund within two months. Justice S.R. Krishna Kumar held that under GST law in India a minor omission in an otherwise compliant delivery challan could not support a detention penalty. He allowed the writ petition filed by Merry Gold against the Union of India and others.
The ruling was delivered in W.P. No. 9284 of 2023. It set aside the original penalty order dated July 15, 2022 and the appellate order dated December 15, 2022. The Court said the failure to list Kundan stones separately in the challan did not make the movement liable under Section 129 of the Central Goods and Services Tax Act, 2017. It rejected the view of the tax authorities that the consignment was meant for sale and not for display as samples.
Challan met Rule 55, stones missed
The jewellery was intercepted while moving with a delivery challan issued under Rule 55 of the Central Goods and Services Tax Rules, 2017. That rule allows movement of goods otherwise than by way of supply, including goods sent as samples, on the cover of a delivery challan with prescribed particulars.
Here the challan described the gold jewellery items and met the requirements of the rule in substance. Field officers objected that Kundan stones fixed in the jewellery had not been mentioned separately. Proceedings were then started under Section 129, which deals with detention, seizure and release of goods and conveyances in transit, and penalty was imposed.
To secure release of the goods, the petitioner paid the amount and challenged the levy. The appellate authority sustained the penalty in December 2022. Before the High Court the petitioner contended there was no attempt to evade tax, the goods were samples and not stock for sale, and a clerical gap in description could not turn compliant movement into movement without proper documents.
On examination of the challan and both orders, the Court found the document was produced at the time of interception and contained the core details required by Rule 55. Absence of a separate line for Kundan stones did not wipe out that challan. The order records no material beyond the omission itself to support the finding that the jewellery was being carried for sale without an invoice.
Court rejects sale assumption
Much of the judgment turns on the difference between goods moved for sale and goods moved as samples. A sale or other supply is normally covered by a tax invoice and, where required, an e-way bill. Samples, goods sent for approval, goods sent for exhibition and similar non-supply movements can travel on a delivery challan under Rule 55.
Authorities had treated the gold jewellery as intended for sale. The Court said that finding was wrong on the facts. A delivery challan was present, the movement was described as samples, and no inquiry had brought out a buyer, a sale price or a transaction. A case of samples could not be converted into a taxable sale only because one component, the Kundan stones, had not been listed separately.
Section 129 exists to check evasion during movement and to permit detention where goods move in contravention of law. The Bench said the power is not meant to visit every paperwork slip with full penalty where the movement is explained and documented. It has to be read with the documents produced at interception and with any indication of intent to move goods without payment of due tax.
In this transit the gold content and jewellery items stood disclosed. The vehicle was not moving without any document, and the goods found were not different from those described. The ingredients for penalty under Section 129 were therefore not made out.
Commentary from top GST law firms in India has often warned that field officers treat any gap in description as a ground for detention, while courts apply a different test of whether the document covers the goods in substance and whether evasion is shown.
Refund within two months
Both the original penalty order and the appellate order stand quashed. The respondents must refund Rs 14,50,560 to the petitioner within two months. The direction covers the full amount collected in the detention proceedings.
Time runs from the date the order is made available to the authorities. In practice the petitioner will place a copy of the High Court order before the jurisdictional officer, after which the sum is to be credited. If payment is not made within the fixed period, the petitioner can seek enforcement in accordance with law, including interest where the statute permits.
Release of the goods had already taken place on payment. The judgment decides only the legality of the penalty retained. Quashing means the two orders do not survive for any other purpose, including for drawing an adverse record against the dealer for that transit.
Finality at the High Court level now attaches to the question whether the Kundan stone omission could sustain a Section 129 charge in this transit. The answer is no. The department must file an appeal in the normal course if it wishes to challenge that view.
Separate action still open
Relief came with one qualification. The Court left the authorities free to start separate proceedings, if warranted, over the alleged mismatch on Kundan stones.
That liberty does not revive the detention penalty. It only permits the department to examine under the correct provision whether any other lapse over disclosure of the stones calls for action. Any fresh case must begin with proper notice, citation of the provision invoked, and a fair chance for the dealer to reply.
Dealers need to grasp the line drawn here. Disclosure of embellishments, stones or other parts is not irrelevant. The Court said only that the omission seen in this transit could not support the detention penalty imposed on the footing of sale. Valuation, declaration or record-keeping issues must be pursued under their own provisions and procedure.
Movement of high-value samples still calls for full description. Careful entry of items, weight and value remains the safer course even when a short description does not attract penalty.
How GST law in India treats samples
Treatment of samples under GST law in India depends on whether there is a supply. Samples moved for display, approval or marketing, without transfer of title or consideration, generally travel on a delivery challan under Rule 55 and not on a tax invoice for sale. The challan must carry date and number, names and addresses of consignor and consignee where applicable, description and quantity, and other prescribed details.
GST law was made applicable in India from 2017, and the framework for non-supply movements under the 2017 Rules has since figured in a large number of detention cases. Courts have separated cases where no document at all is produced from cases where a document is produced but is called defective in a minor detail.
This ruling falls in the second group. The challan existed and covered the jewellery, and the missing mention of Kundan stones did not change the character of the movement from samples to sale. That reading follows Rule 55, which looks to sufficient disclosure for verification, and Section 129, which looks to contravention linked to evasion.
Dealers who carry catalogues, display kits and approval stock will rely on the order, especially in jewellery, textile and consumer goods trades where samples move between branches, agents and exhibitions. Officers must assess the challan as a whole and record material for treating samples as sales instead of acting on inference alone.
Section 129 detention power explained
Section 129 of the Central Goods and Services Tax Act, 2017 permits detention of goods and conveyances transported in contravention of the Act or the rules. Once contravention is found, penalty becomes payable for release. An appellate remedy is provided, and it was used in this case before the High Court was moved.
High Courts have said in recent years that detention is not automatic for every error. They ask whether the required document accompanied the goods, whether the description broadly tallies, whether the e-way bill where needed was valid, and whether material points to intent to evade tax. Technical slips without more have in several cases been held insufficient for full penalty.
The Karnataka High Court applied that test. It did not hold that Rule 55 challans need not describe stones or parts. It held the penalty chosen by the authorities, imposed on the footing of sale, did not fit the lapse proved. A penalty built on sale must rest on material showing sale or preparation for sale, not only on an incomplete line in a challan.
For officers the procedure is to record the exact mismatch, seek an explanation on the spot, verify weight and value where possible, and then decide whether detention penalty or a different proceeding is called for. For dealers the practice is to carry the original challan, enter item-wise description, weight and value, and keep proof of purpose such as a letter for exhibition or approval to show the non-supply nature if stopped.
The petitioner now waits for the refund of Rs 14,50,560 within the two months fixed by the Court, with the department left only with limited liberty to pursue by separate notice any other case it claims arises from non-disclosure of the Kundan stones.
Comments
Sign in to read the discussion and share your thoughts.
Latest from LawWorld
News
View all- Supreme Court Seeks Centre, ECI Reply On Plea Against Immunity For CEC And ECs4 Nov 2026
- Supreme Court Directs MP Speaker To Decide Bina MLA Disqualification Plea In Two Months4 Nov 2026
- Supreme Court Orders Special Cell To Monitor Child Labour Law Enforcement4 Nov 2026
- Bail Cannot Rest On Judge's Personal Notions Of Morality, Rules Supreme Court4 Nov 2026
- Supreme Court Refers Two-Child Norm Penalties To Larger Bench As Outdated4 Nov 2026